Affordability with no payroll and no credit history
Calculate how much an informal worker has left each month: their income and expenses, validated against their profile, minus their debts. No documents, no credentials.
Book your demo
56.2%: INEGI, National Occupation and Employment Survey (ENOE), July 2026. The other figures describe the service.
work in the informal economy
informal trades
states covered
documents required from the applicant
A ride-hailing driver in Mexico City earns MXN 7,000 to 10,500 net per month (Tracción, 2026), and an informal worker earns MXN 8,364 on average (INEGI, ENOE, Q1 2026).
How it works
Three ways to integrate it: REST API · batch (upload your file) · Finvero origination flow.
Ride-hailing driver
Real anonymized case
- INEGI · ENOE
- INEGI · ENIGH
- Geo-economic data
- Digital footprint
2. We enrich the profile
We match the profile against official INEGI sources and alternative sources.
4. You decide and monitor
Your engine applies your liquidity rules and you monitor every result in Finvero.
Your policy calculates affordability from what the customer declares
Declared income comes in inflated
With no payroll or social security record to check against, the income the applicant reports goes straight into your calculation. You approve amounts their daily work cannot support.
Declared expenses come in trimmed
Applicants who want the loan report lower expenses than it costs to support their family. Affordability gets inflated a second time, now from the other side.
No proof: reject or visit
To play it safe, you reject the informal worker or send someone to verify. You lose a good payer or pay a per-application cost the loan amount does not justify.
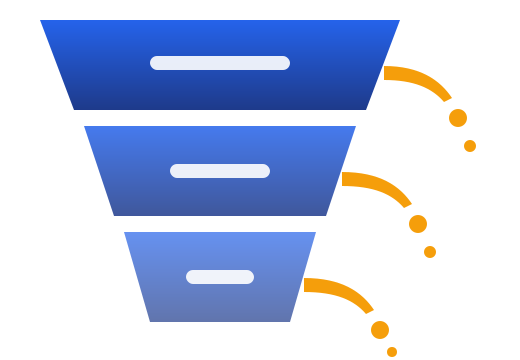
- 01Declared income comes in inflated
- 02Declared expenses come in trimmed
- 03No proof: reject or visit
What your operation gains
Lend to those you reject today
Taxi drivers, construction workers, vendors and 47 other trades get a calculated affordability instead of a rejection for lack of proof.
Declared figures stop being the data
Income is capped at the profile p75 and expenses are floored at the p25. Every query shows what was adjusted and why.
No visits to verify income
Affordability arrives with the application. Your team reviews only the cases your policy flags, not every informal file.
API, batch or Finvero flow
Integrate via REST API, upload your portfolio in batch or turn it on in the Finvero origination flow, within Score as a Service.
Comparison by provider category
| Credit history-based estimators | Connection-based income verifiers | Finvero | |
|---|---|---|---|
| What they ask of the applicant | Credit history | Connected payroll, platform or bank account | Data the application already has |
| What they deliver | Income or index | Verified income | Income, expenses and affordability |
| Informal worker with no history or bank account | Out of scope | Out of scope | Covered |
| Origination channel and lender network | Not included | Not included | On the same platform |
Who uses it
Microcredit
Affordability for vendors and tradespeople without proof of income, with no verification visit for each application.
Auto
Affordability for ride-hailing and taxi drivers to set down payment, amount and term with validated data.
Retail credit
Affordability at the checkout for customers who pay cash and have no payroll or credit history.
Smartphone financing
Affordability to finance devices for self-employed workers using the application data.
Consumer lending
Validation of declared income and expenses in personal loans to independent workers.
Voices from Operations
“My informal applicants declare whatever they want and I have nothing to check it against.”
 Chief Risk Officer
“I am rejecting good payers just because they don’t bring a pay stub.”
 Chief Commercial Officer
“Every verification visit costs me more than the loan brings in.”
 Chief Operating Officer
“I need to add it without rebuilding my flow: one more call, not a project.”
 CTO
What your vendor questionnaire will ask
Consent
Processing under Mexico’s LFPDPPP, with the applicant’s express consent to query their digital footprint and ARCO rights.
Traceability
Every query is logged with its inputs, sources, table version and result.
Encryption and access
Encryption in transit and at rest, role-based access control and an operations log.
Your data
It is not used to train third-party models.
Auditability
Every affordability result comes with its breakdown: validated income and expenses, adjustments applied and reference level.