Static vs. Static Rules Machine Learning: The evolution in the prevention of financial fraud


Insights by Finvero
Preventing financial fraud has always been an arms race between financial institutions and cybercriminals. For years, the cornerstone of any defense system has been models based on static rules. If a transaction meets certain predetermined conditions (for example, it occurs in the early morning, exceeds $10,000 USD, and originates from a high-risk country), the system blocks it. However, as fraudsters develop more sophisticated tactics and automated tools, this linear approach has become painfully obsolete.
The limit and hidden costs of Static Rules
The main problem with static rules lies in their absolute rigidity. These systems work extremely well at blocking known and predictable attack vectors, but are completely blind to zero-day fraud threats. Today's fraudsters reverse engineer these rules, quickly figuring out how to circumvent them by fragmenting transactions or simulating legitimate behavior.
Even worse is the operating cost they generate. Static rules are primarily responsible for false positives: perfectly legitimate transactions that are rejected in error. Each false positive not only represents a direct loss of revenue, but also deep frustration for the customer, increasing the abandonment rate or churn. Additionally, maintaining these systems requires entire teams of risk analysts to manually review and adjust the rules week after week, making the system costly and reactive.
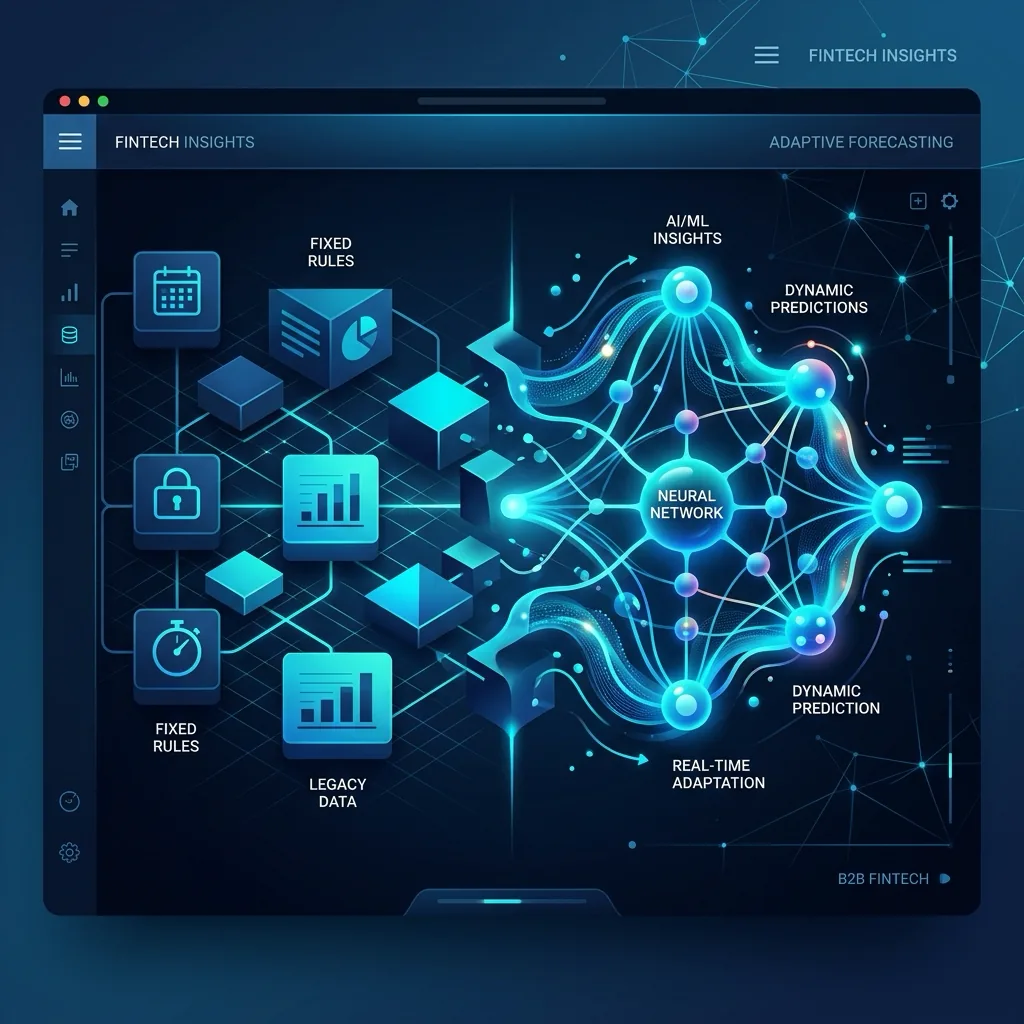
Machine Learning: Dynamic, Contextual and Real-Time Prevention
This is where artificial intelligence and, more specifically, Machine Learning (ML) changes the rules of the game. Unlike rigid “if this, then that” rules, ML algorithms do not operate in a static framework. These models continually learn by processing billions of structured and unstructured data points.
Machine Learning analyzes the full context of a transaction in milliseconds. It evaluates hundreds of variables simultaneously: from user browsing behavior, typing speed, device fingerprint and cross-referenced geolocation to historical spending patterns. By doing so, it generates a dynamic, hyper-personalized risk score that cannot be replicated with simple conditional rules.
Actionable Insights for Modern Defense
Drastic reduction in False Positives: By understanding the context and nuances of human behavior, ML distinguishes with unprecedented precision between a legitimate holder traveling abroad and an actual fraud attempt. This increases approval rates and improves customer retention.
Adaptability and Continuous Self-Learning: Machine Learning models (such as neural networks or random forests) are retrained with the most recent data. This allows them to detect subtle anomalies and emerging fraud tactics without requiring a human to write a new rule.
Unprecedented Operational Scalability: An ML-powered engine can process massive spikes in transactions (such as Black Friday) without degrading performance or requiring a linear increase in fraud analyst staff. The human team can then focus on complex investigations, not manual classification.
Conclusion
The transition from static rule-based engines to Machine Learning-driven ecosystems is no longer a "technological luxury" reserved for global banks; it is an essential qualitative leap for the survival of any modern lender or merchant. Attackers are already using AI to breach systems, and the only way to combat this is with superior AI.
At Finvero, we understand this urgency. Our architecture and ecosystem integrate cutting-edge risk engines to ensure that your credit origination, payments and embedded finance processes operate under the highest standards of security and zero friction, minimizing your risk exposure while maximizing your growth.