How to Reduce the Impact of Identity Fraud in the Financial Industry


Digitalization is a key driver that opens a significant gap and increases the impact of fraud on the financial industry. Read our full article: is the user experience at risk?
El fraude de identidad es una de las principales amenazas para la industria financiera, afectando a prestamistas, comercios y consumidores por igual. A medida que la digitalización avanza, los delincuentes también evolucionan, aprovechando brechas tecnológicas y la falta de controles robustos para cometer fraudes. Según el Global Fraud and Identity Report 2024, el fraude de identidad ha crecido un 20% en los últimos dos años, con más del 50% de las entidades financieras reportando pérdidas significativas más del 50% de las entidades financieras reportando pérdidas significativas. Ante este panorama, la industria debe adoptar estrategias tecnológicas avanzadas para minimizar riesgos sin comprometer la experiencia del usuario.
Main Types of Identity Fraud in the Financial Sector
Before exploring solutions, it is key to understand the types of identity fraud that affect the financial sector:
-
Identity Theft: Theft of Personal Information
-
Increase in delinquencies on loans granted to stolen identities.
-
Additional costs in fund recovery and legal disputes.
-
Reputational damage and loss of trust among affected customers.
-
In 2023, the Federal Trade Commission (FTC) reported more than 1.1 million identity theft cases in the U.S., with estimated losses of $10.2 billion from financial fraud alone.
-
Synthetic Identities: The Perfect Forgery
-
Multimillion-dollar losses from granting loans to nonexistent identities.
-
Higher recovery costs and fraud forensic analysis costs.
-
Greater exposure to fraud risk without a real-time data validation system.
-
Synthetic identity fraud accounted for $6 billion in losses for the U.S. financial system in 2023, making it the fastest-growing type of credit fraud.
-
Account Takeover (ATO): Theft of Access Credentials
-
Millionaire frauds in unauthorized transactions.
-
Loss of customer trust in the security of their accounts.
-
Legal risk from noncompliance with data protection regulations.
-
ATO fraud in e-commerce increased 282% over the past five years, with more than 5 billion attacks recorded in 2023 on digital payment platforms alone.
-
Fraud in Credit Applications: Altered or False Documentation
-
Increase in uncollectible loans, affecting the balance sheets of financial institutions.
-
Need for greater investment in identity and document validation.
-
Increased risk of systemic fraud at institutions with weak verification processes.
-
In Latin America, 15% of loan applications contain some type of altered or fraudulent information, representing losses of billions of dollars for the financial sector.
How does it happen?
Criminals obtain stolen personal data (such as names, addresses, tax identification numbers, or bank accounts) and use it to apply for loans or carry out fraudulent transactions.
Impact on the financial sector:
How does it happen?
Fraudsters combine real information with fake data to create a completely new identity that is difficult to trace and detect. This type of fraud is particularly dangerous because traditional impersonation alerts do not easily detect it.
Impact on the financial sector:
How does it happen?
Cybercriminals obtain login credentials for bank accounts or lending platforms through techniques such as phishing, malware, credential theft on the dark web, or social engineering attacks. Once inside, they make fraudulent transfers, unauthorized purchases, or change key data to lock out the legitimate account holder.
Impact on the financial sector:
How does it happen?
Fraudsters submit loan applications with altered data, forged documents, or inflated income to access loans they would not otherwise qualify for. In many cases, they also use stolen or synthetic identities to strengthen their credibility.
Impact on the financial sector:
Key strategies to reduce identity fraud
To mitigate the impact of identity fraud in the financial industry, it is essential to combine technology, data analytics, and best practices. Here are some effective strategies:
1. Implement advanced biometrics
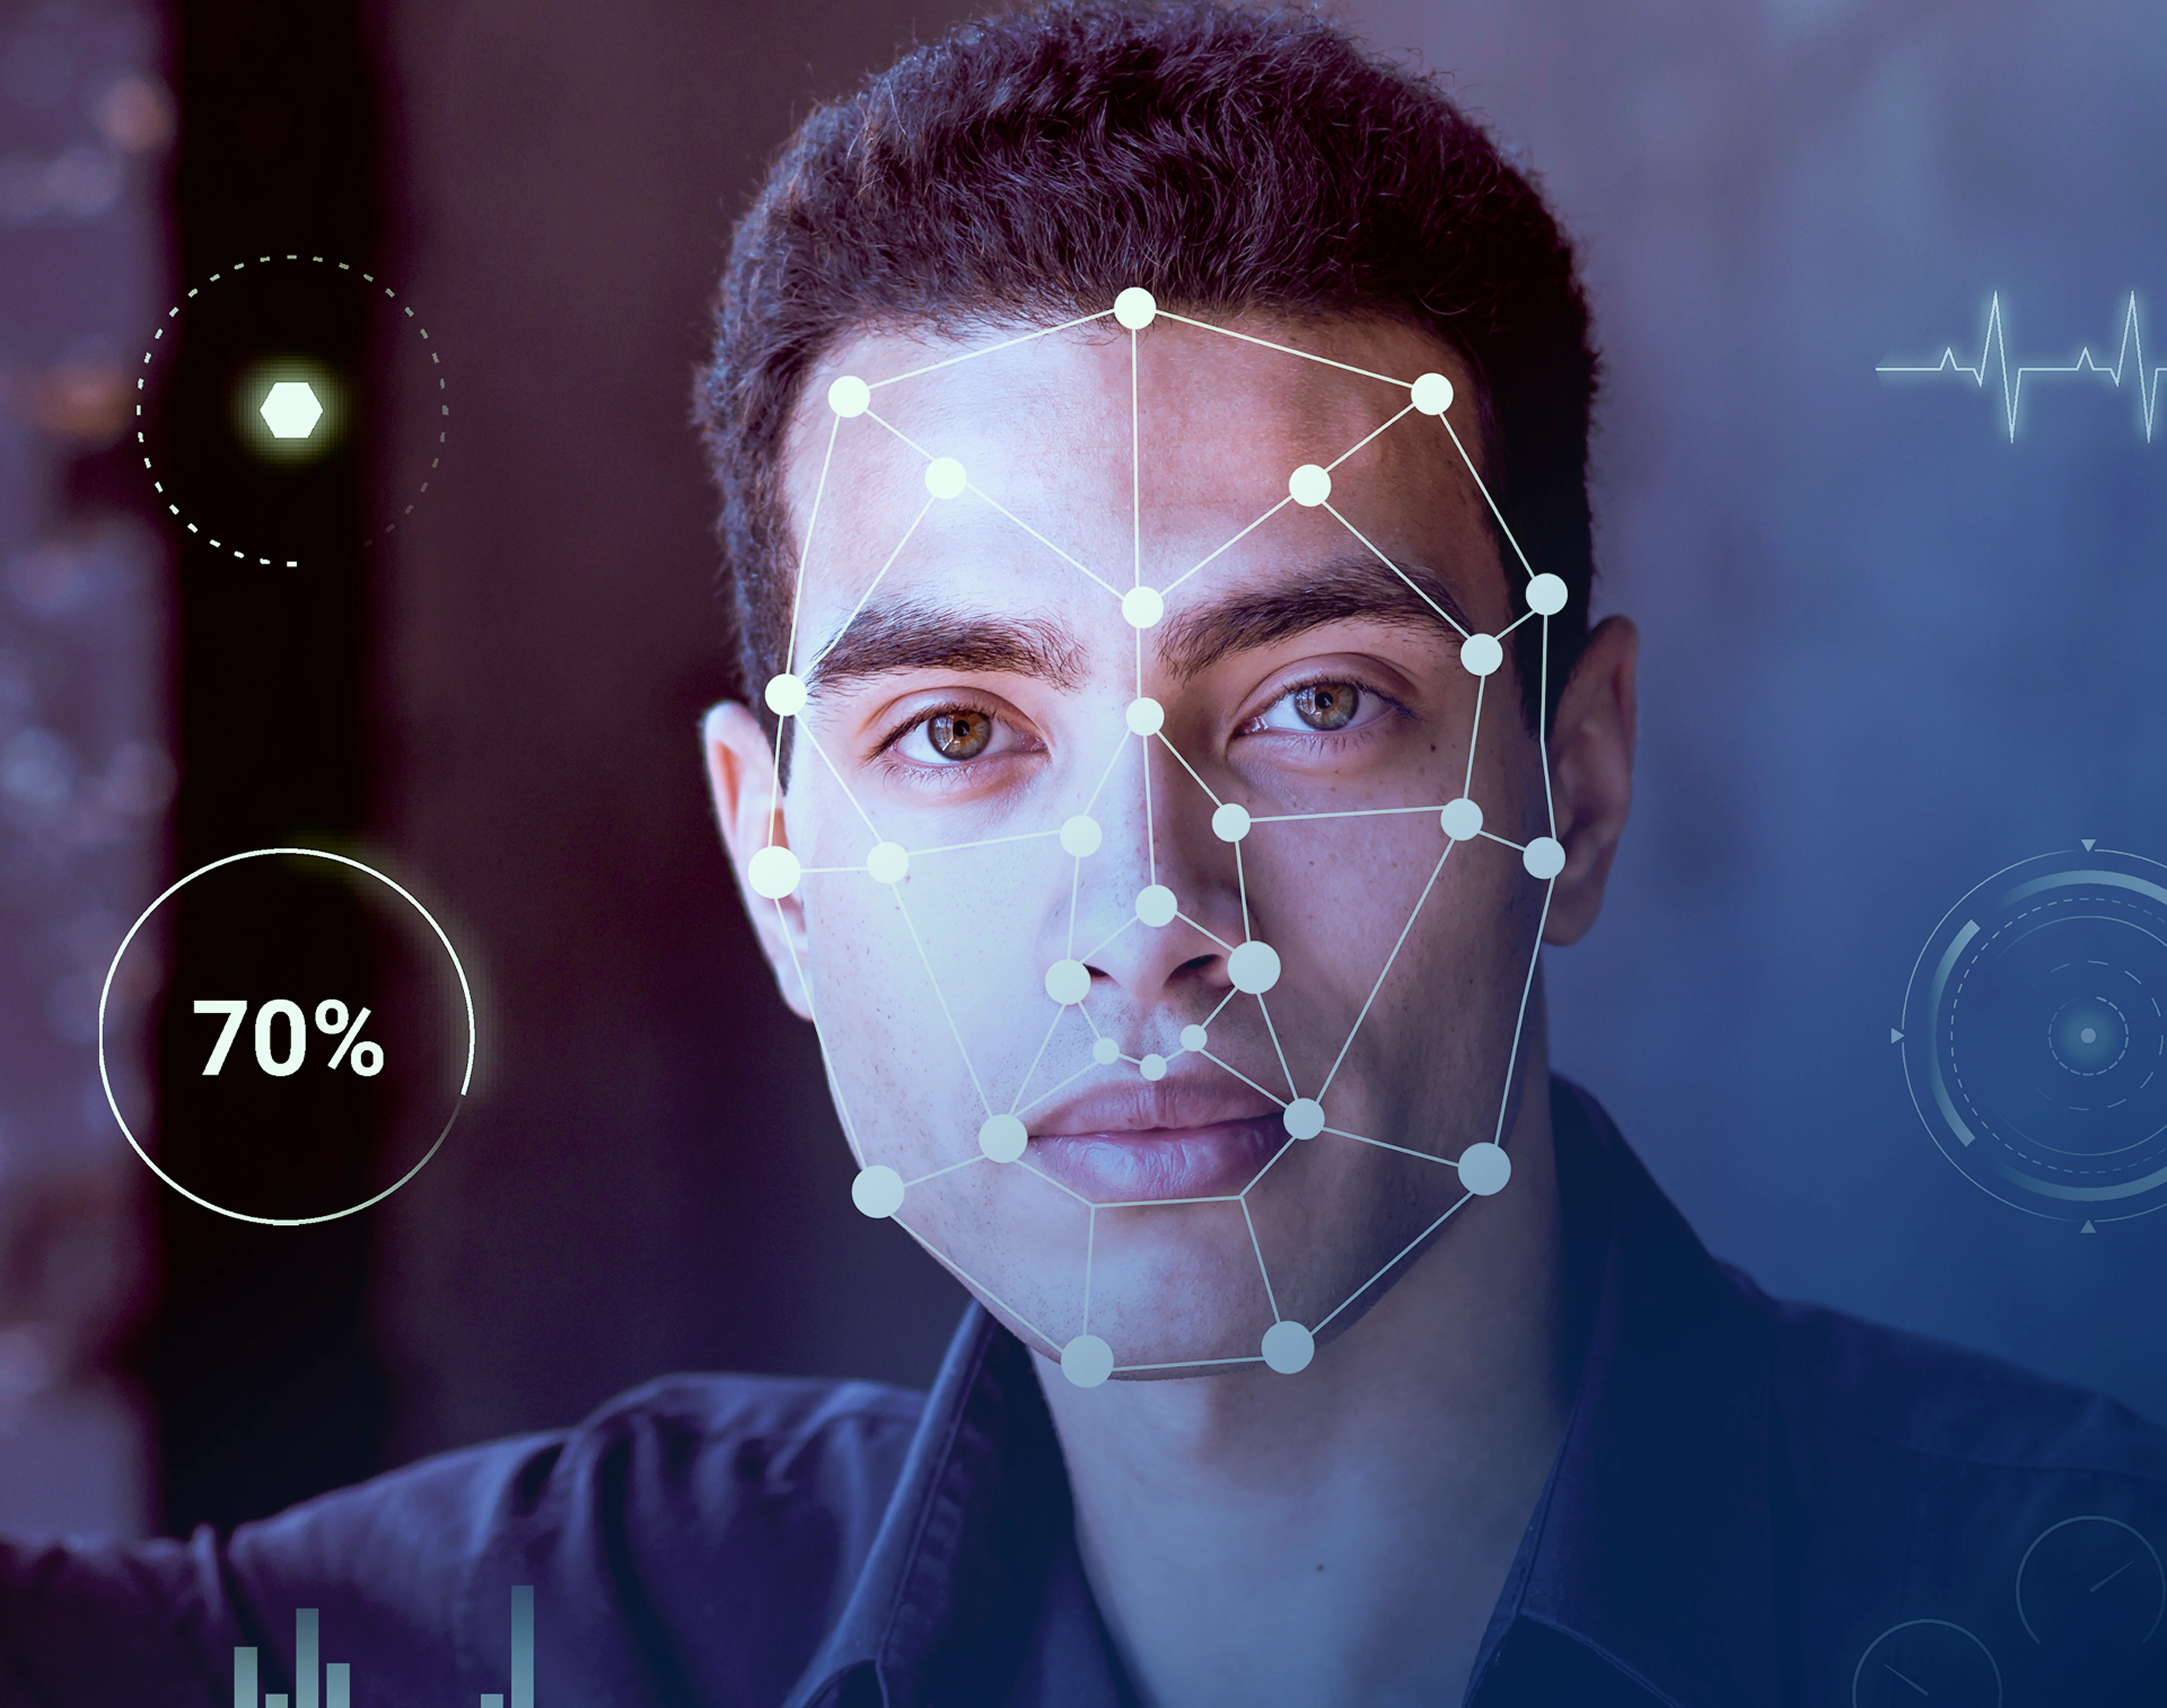
Biometric authentication systems, such as facial recognition, fingerprints, and voice scanning, have proven highly effective at preventing fraud. These technologies ensure that the person applying for the loan or making a transaction is who they claim to be. For example, Finvero uses facial biometrics to verify users' identity in seconds, reducing the risk of impersonation.
2. Leverage Machine Learning for Predictive Analytics
Artificial intelligence makes it possible to detect suspicious patterns before fraud occurs. Machine learning algorithms analyze large volumes of data to identify anomalous behavior and predict fraud attempts in real time. Our machine learning models analyze more than 1,000 variables to detect suspicious activity with 95% accuracy.
3. Implement an Alternative Fraud Score
Unlike traditional systems, an Alternative Fraud Score analyzes variables such as digital behavior, device usage, and transaction patterns to detect signs of fraud before it occurs. This approach enables financial institutions to make more informed decisions and reduce the risk of losses.
4. Real-time transaction monitoring
Financial platforms must have real-time monitoring systems that detect suspicious activity instantly. Combining predefined rules with AI-based detection makes it possible to stop fraud before it happens. Finvero has implemented a monitoring system that analyzes more than 10,000 transactions per second, blocking fraudulent activity within milliseconds.
5. Multi-factor authentication (MFA)
Adding security layers such as two-step verification (2FA) or multifactor authentication dramatically reduces the risk of unauthorized access to financial accounts. Finvero integrates MFA into all its processes, ensuring that only authorized users can access their accounts.
6. Use of alternative data for identity verification
Financial institutions can complement traditional identity verification with alternative data, such as utility payment history, social media, and online behavior, to strengthen their approval models. At Finvero, we use alternative data to create more accurate risk profiles and reduce fraud in loan applications.
7. Educate customers and employees about fraud
Financial institutions must train their customers and employees to detect fraud attempts and phishing alerts, and to follow safe practices for handling personal information and credentials. Finvero offers webinars and practical guides to help its users protect themselves against fraud.
The future of fraud prevention.
As identity fraud continues to evolve, the strategies to combat it must evolve too. Combining advanced technology, such as AI and biometrics, with a proactive approach to data analytics and real-time monitoring will make the difference in the security of the financial sector.
At Finvero, we are transforming the industry with innovative solutions that make credit safer and more accessible. Our AI-based platform makes it possible to assess risk and detect fraud in real time, protecting both lenders and users. With tools such as the Alternative Fraud Score and advanced biometrics, we are leading the fight against identity fraud.
Conclusion
Identity fraud is a complex challenge, but with the right tools and strategies, its impact can be minimized. Financial institutions must take a proactive approach, combining advanced technology, education, and collaboration with users. At Finvero, we are committed to security and innovation, offering solutions that protect everyone in the industry.
Ready to protect your business and your customers?
Discover how Finvero can help you fight identity fraud with our cutting-edge technology solutions.