How to Improve Accuracy in Credit Risk Analysis to Reduce Financial Losses
October 09, 2025 - Lenders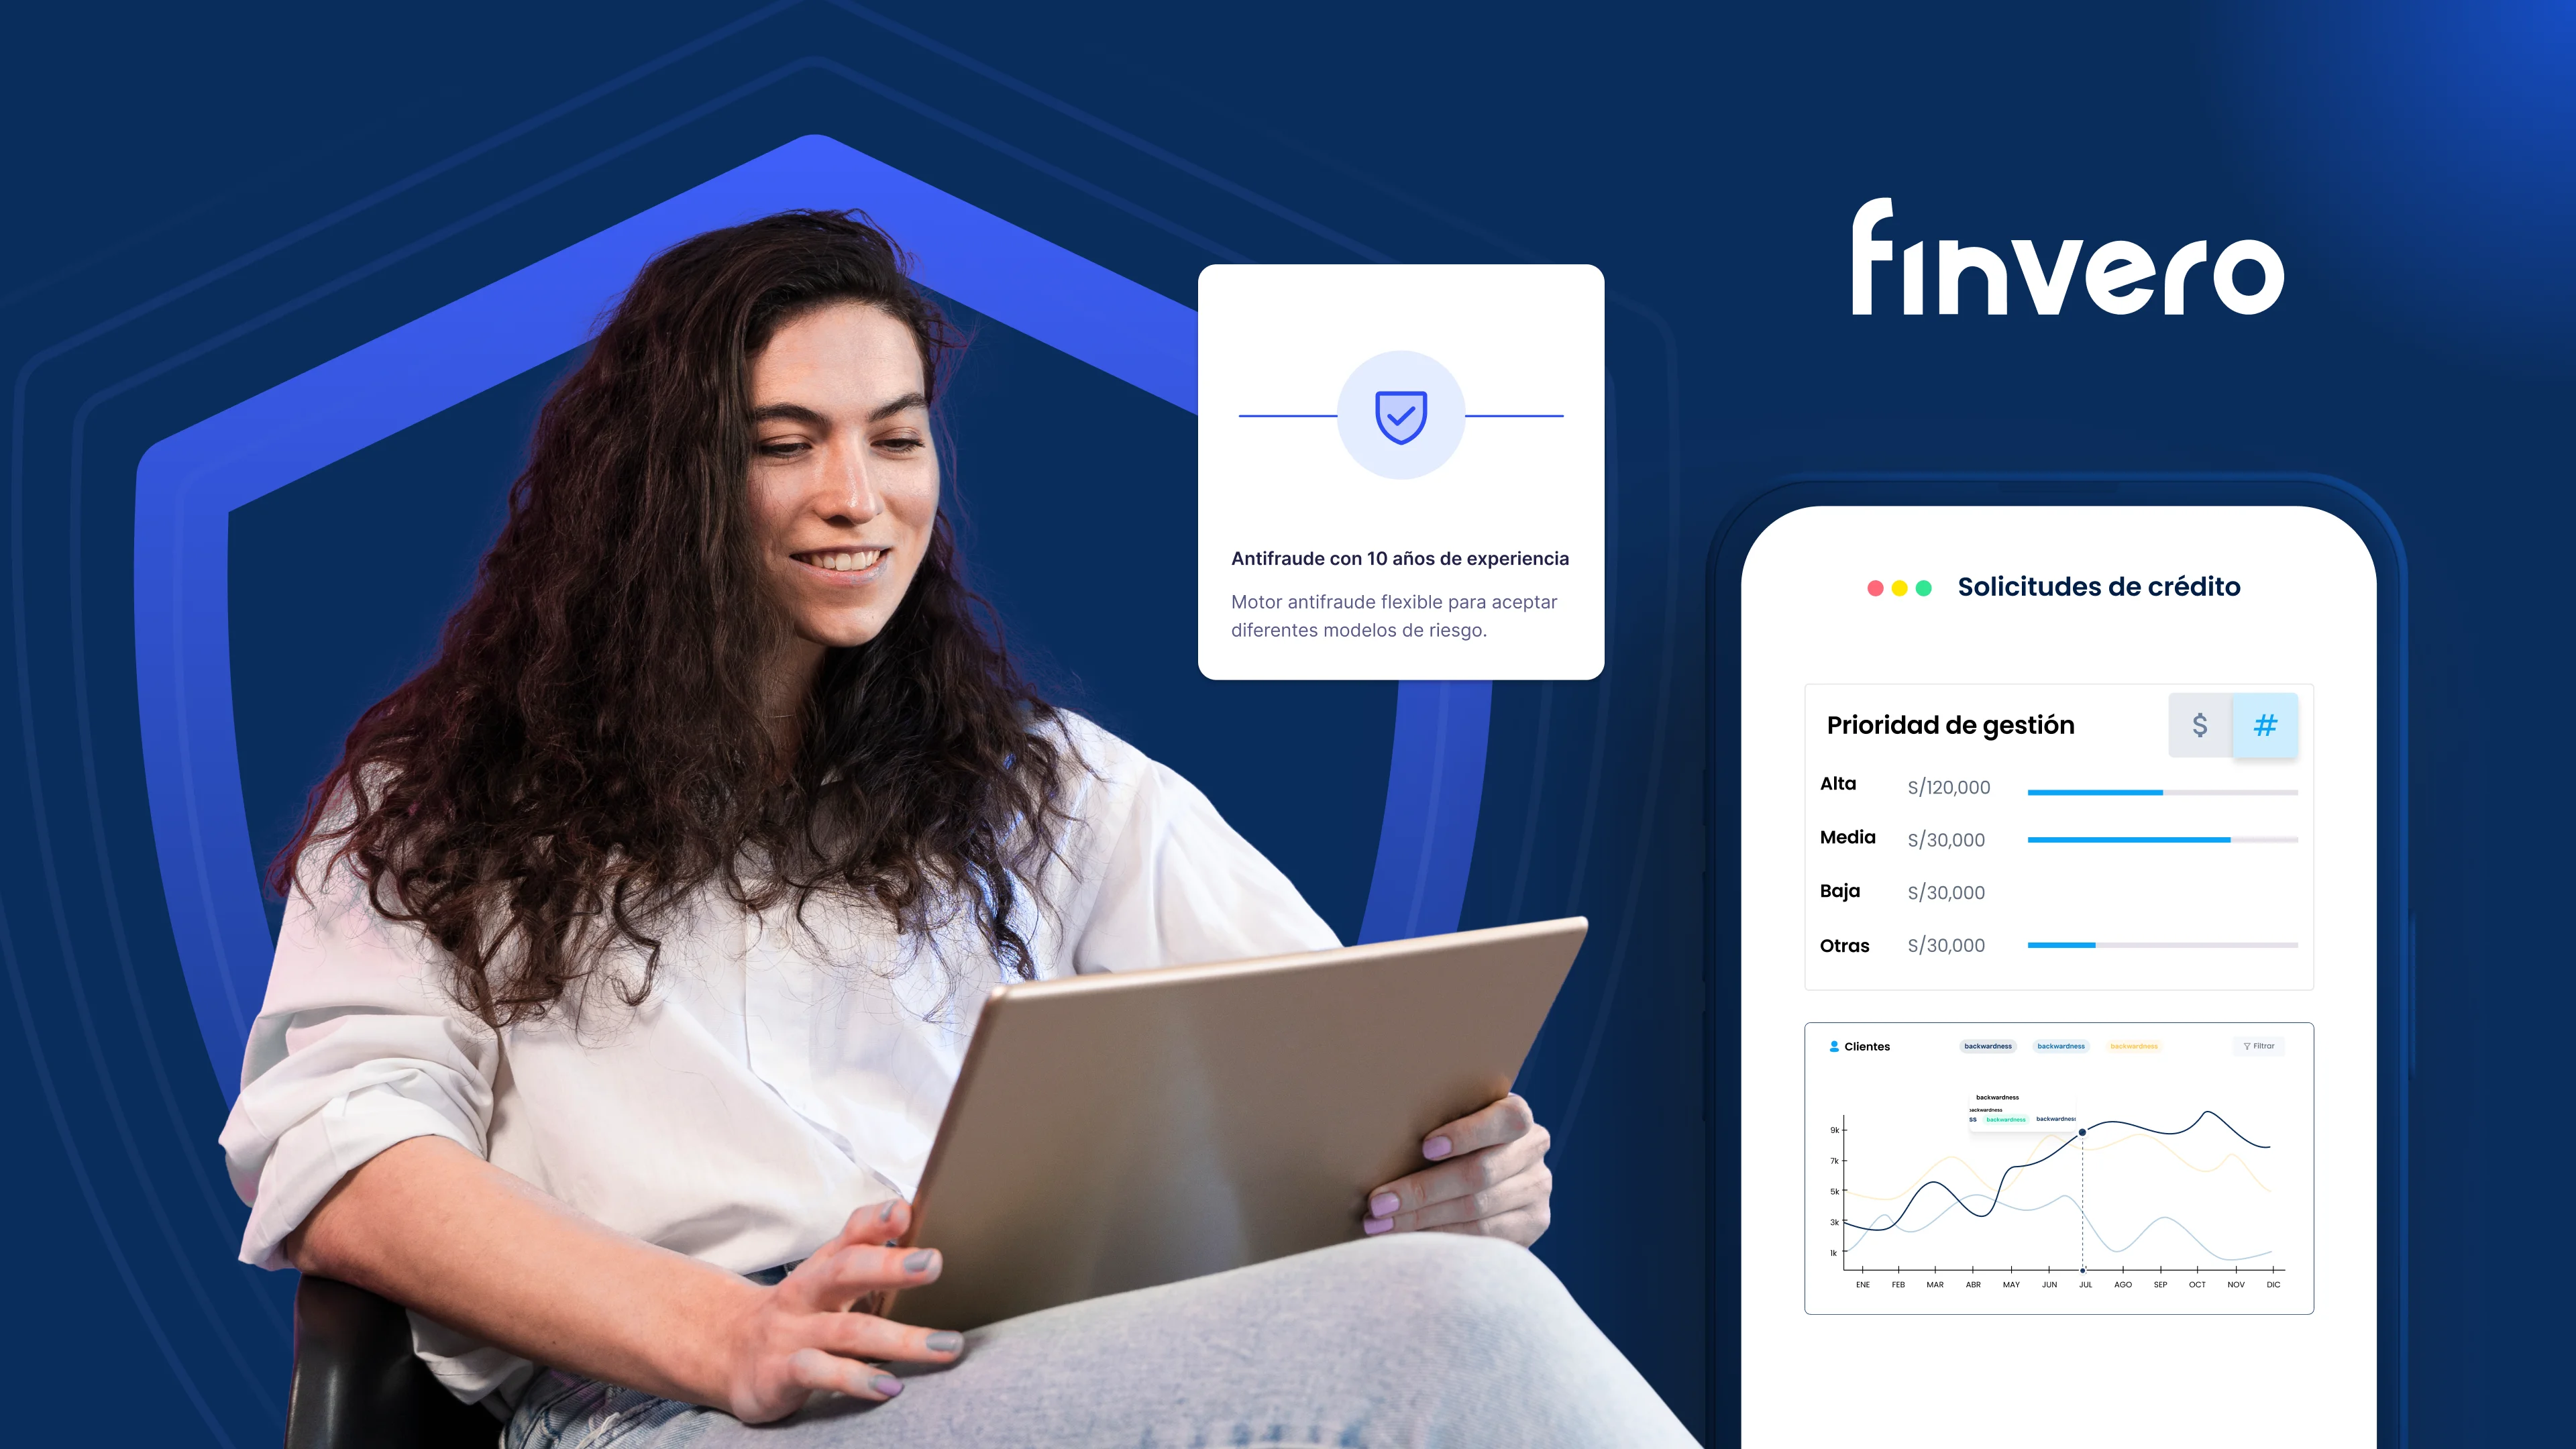
La falta de precisión en el análisis del riesgo crediticio es uno de
los mayores desafíos que enfrentan los bancos, prestamistas e
instituciones financieras que otorgan créditos. Según datos del Banco
Interamericano de Desarrollo (BID), desde 1996 hasta 2023, BID Invest
registró una baja tasa de morosidad media del 1.8%, destacando la
importancia de una gestión de riesgos precisa y
effective. Sin embargo, en el contexto más amplio de América Latina, la
morosidad bancaria ha alcanzado tasas cercanas al 2%, evidenciando que
aún hay margen para mejorar la calidad de los
credit analysis.
En un mercado donde el acceso al crédito es esencial
para el crecimiento económico, optimizar los modelos de evaluación del
riesgo no solo protege los ingresos, sino que también fomenta la
estabilidad y la inclusión financiera.
The Problem: Inaccurate Credit Risk Assessments
Credit risk assessments are crucial for any bank or financial institution, since they determine customers' ability to meet their financial obligations. However, when these assessments are inaccurate, the consequences can be devastating:
- Increased delinquency: Inaccurate assessments lead to extending credit to high-risk profiles.
- Financial losses: Every unpaid loan represents a direct loss of revenue and affects financial statements.
- Reputational impact: Recurring errors erode the trust of investors and customers.
Fortunately, emerging technologies such as artificial intelligence (AI) and alternative data analysis offer a unique opportunity to improve the accuracy of risk assessment and mitigate these challenges.
5 Solutions to Reduce Financial Losses
- Implement Customized Risk Models
Traditional credit scoring models may be insufficient to capture the complexity of financial behavior. Adopt tools that use generative AI and alternative data, such as spending patterns or online behavior, to develop models that are more accurate and tailored to each profile. - Incorporate Alternative Data
Beyond traditional credit histories, using data such as on-time payment of basic utilities (electricity, water) and purchasing patterns can provide a more complete picture of the customer. This improves risk assessment and significantly reduces the likelihood of delinquency. - Automate the Evaluation Process
Automation reduces human error and enables faster decisions. There are technology platforms that make it easier to manage the credit lifecycle, from application to collections, ensuring greater efficiency and more consistent results. - Continuous Portfolio Monitoring
Customers' financial conditions change over time. Implementing systems that run periodic assessments makes it possible to identify emerging risks in the portfolio and take preventive action before problems escalate. - Financial Training and Education for Customers
Prevention starts with education. Providing resources so customers understand the terms of their credit and manage their personal finances properly helps reduce default risk and strengthens the relationship with the financial institution.
The Future of Credit Risk Analysis: Toward a Sustainable Financial Ecosystem
In a highly competitive environment, banks and lenders must adopt advanced tools such as artificial intelligence, alternative data analysis and automation to transform their credit assessment processes. These technologies not only help minimize risk and protect balance sheets, but also improve the customer experience by delivering fairer, more personalized assessments. Accuracy in credit analysis thus becomes a key factor in building trust and fostering sustainable customer relationships, strengthening institutions' reputation as responsible and efficient players.
Despite the associated challenges, such as the initial investment, staff training and compliance with ethical and privacy regulations, the benefits of these innovative approaches far outweigh the costs. The ability to anticipate market trends, democratize access to credit and drive financial inclusion will position industry leaders as pioneers in building a more resilient, equitable and future-oriented financial system. Adopting these technologies is not just a competitive strategy, but an opportunity to lead the industry's transformation toward a more positive economic and social impact.
Is your institution facing challenges in credit risk assessment?
Finvero is a platform with which you can optimize loan management from origination to collections, using advanced technology such as generative AI and alternative data. Request a free demo today and take your credit strategy to the next level. Find out how!
 Facebook
 Linkedin
 Instagram
 Whatsapp